
Laporan Keuangan
Don't Miss the Deadline! Annual GMS Reporting Obligations and Penalties Under Minister of Law Regulation No. 49 of 2025
In conducting business, a limited liability company must pay attention not only to its operational and financial activities but also to its administrative obligations and legal compliance. One important aspect is the reporting of the approval of the annual report through the General Meeting of Shareholders (GMS).
These requirements are governed by Regulation of the Minister of Law of the Republic of Indonesia Number 49 of 2025 concerning the Requirements and Procedures for the Establishment, Amendment, and Dissolution of Limited Liability Companies. The regulation sets out reporting procedures, submission deadlines, and sanctions for companies that fail to fulfill their obligations.
1. When Must the Annual Report Be Submitted?
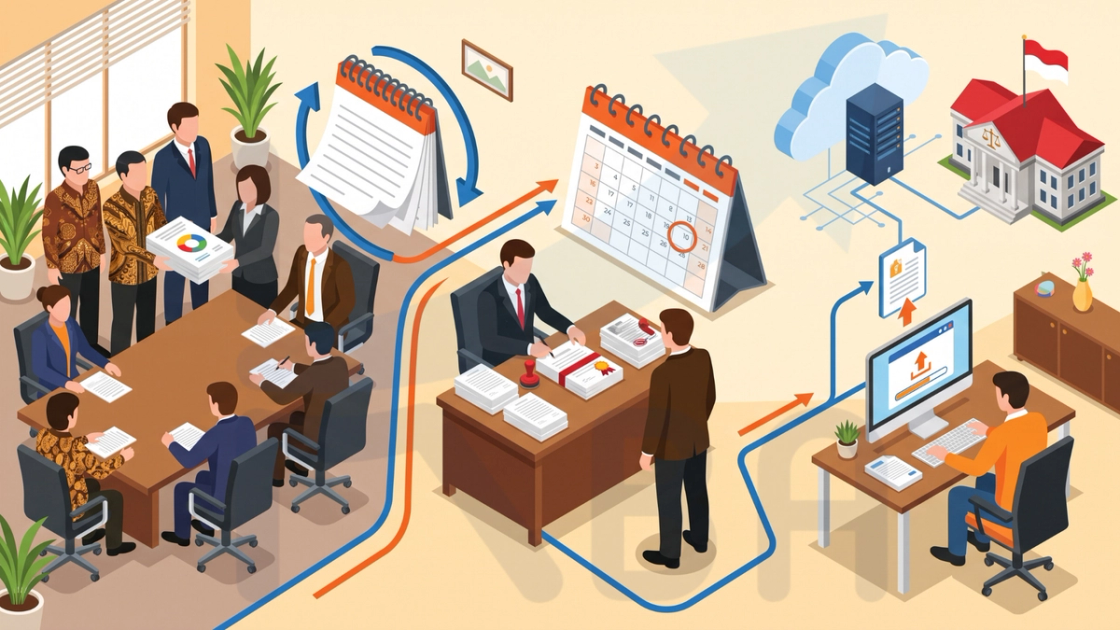
Under Article 16 of Minister of Law Regulation No. 49 of 2025, the Board of Directors of a capital partnership company must submit the annual report to the GMS after it has been reviewed by the Board of Commissioners. The report must be submitted no later than six months after the end of the company's financial year.
Approval of the annual report by the GMS must be documented in a notarial deed. The Board of Directors, through a notary, must then submit the approval to the Minister no later than 30 calendar days from the date the notarial deed is signed.
The reporting process must be completed electronically through the Legal Entity Administration System (SABH), together with the required supporting documents.
2. What Must the Company's Annual Report Include?
The annual report submitted to the GMS must provide information about the company's condition and activities. Under Article 16 paragraph (6), the report must include at least:
- Financial statements, including the statement of financial position, income statement, cash flow statement, statement of changes in equity, and notes to the financial statements.
- A report on the company's business activities.
- A report on the implementation of social and environmental responsibility.
- Details of issues affecting the company's business activities during the financial year.
- A report on the supervisory duties of the Board of Commissioners.
- The names of the members of the Board of Directors and the Board of Commissioners.
- Salaries, allowances, or honoraria of the members of the Board of Directors and the Board of Commissioners for the preceding financial year.
Complete and accurate information is essential to the approval of the annual report and its subsequent submission to the Minister.
3. How Does the Reporting Process Work?
The approval of the annual report must be reported electronically through SABH by the Board of Directors through a notary. The principal documents required are:
- The notarial deed documenting the approval of the annual report.
- The company's annual report.
Once the notification has been received, the Minister, through the Directorate General of General Legal Administration (AHU), issues a notification receipt in accordance with the applicable provisions.
Companies should therefore ensure that their annual reports are prepared, approved at the GMS, documented in a notarial deed, and submitted within the prescribed deadline.
4. What Are the Penalties for Late Reporting?
Companies that fail to fulfill their reporting obligations or submit the required documents late may be subject to administrative sanctions under Articles 17 and 18 of Minister of Law Regulation No. 49 of 2025.
These sanctions include:
- Written warning, delivered through SABH notifications and/or email.
- Blocking of SABH access if the company fails to fulfill its obligations within 30 days of receiving the warning.
Blocked access may hinder the company's ability to complete administrative procedures through SABH. To restore access, the company must submit an application through SABH and provide the required documents. Access may be restored once the application has been received and deemed complete.
5. What About Individual Companies?
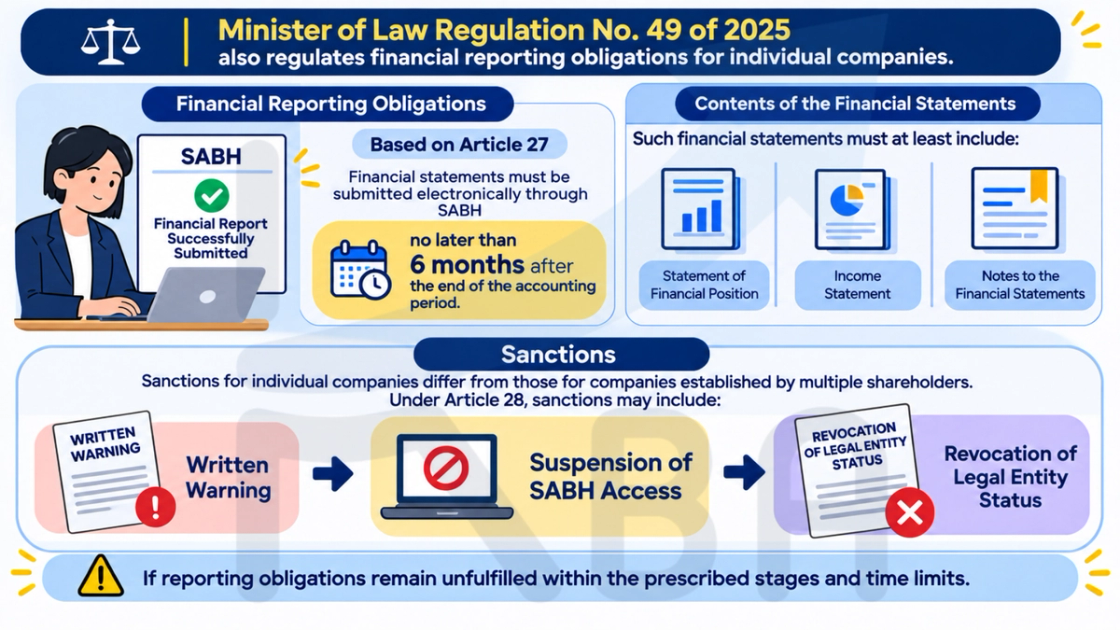
Minister of Law Regulation No. 49 of 2025 also governs financial reporting obligations for individual companies. Under Article 27, financial statements must be submitted electronically through SABH no later than six months after the end of the accounting period.
These financial statements must include at least a statement of financial position, an income statement, and notes to the financial statements.
The sanctions applicable to individual companies differ from those applicable to capital partnership companies. Under Article 28, sanctions may include written warnings, suspension of access, and ultimately revocation of legal entity status if the reporting obligations remain unfulfilled within the prescribed stages and time limits.
6. The Importance of Corporate Administrative Compliance
These provisions demonstrate that preparing an annual report and reporting its approval are not merely formalities. Companies must pay attention to the GMS schedule, the completeness of their reports, the preparation of notarial deeds, and the deadlines for submitting documents through SABH.
Maintaining orderly corporate records and regularly monitoring reporting deadlines can help companies reduce the risk of late submissions and administrative sanctions.
Conclusion
Minister of Law Regulation No. 49 of 2025 emphasizes the importance of complying with annual report approval and financial reporting obligations according to the company's legal form. The Board of Directors should ensure that every required step is completed on time to maintain proper corporate legal administration and avoid disruptions to SABH access resulting from non-compliance.
Legal basis: Regulation of the Minister of Law of the Republic of Indonesia Number 49 of 2025, particularly Articles 16–20 and Articles 27–28.
Tax support for companies in Malang City and Malang Regency, from the KBA Consultant office in Kota Batu, is on the tax consultant in Malang page.