
Pelatihan
KBA Consultant Conducts Tax Training: An In-Depth Review of Corporate Tax Return Amendments in the Coretax Era
The transformation of Indonesia’s tax administration system through Coretax DJP has brought various adjustments to the process of fulfilling taxpayers’ tax obligations. One area that requires particular attention and accuracy is the amendment of the Annual Corporate Income Tax Return (SPT Tahunan PPh Badan). Errors in figures, unreported transactions, changes to financial statements, fiscal reconciliation errors, or tax credits that have not been taken into account may cause the information in a previously filed tax return to no longer accurately reflect the taxpayer’s actual circumstances.
KBA Consultant’s training equips participants with hands-on knowledge of how to accurately amend and file the Annual Corporate Income Tax Return in the Coretax era.
Recognizing the importance of this understanding, KBA Consultant conducted a Tax Training Program focusing on Amendments to the Annual Corporate Income Tax Return through Coretax DJP. The training was designed to provide participants with a practical and systematic understanding, enabling them not only to operate the Coretax system but also to understand the analytical process that should be undertaken before an amendment is made.
Why Is an SPT Amendment Necessary?
An SPT amendment is an action taken by a taxpayer to correct a previously filed tax return when it is subsequently identified that certain data, information, calculations, or reporting were inaccurate or incomplete. Circumstances that may require an amendment include calculation errors, unreported transactions, duplicate transactions, incorrect account classifications, unrecorded fiscal adjustments, changes to financial statements, depreciation or amortization errors, as well as tax credits that have not been properly taken into account.
However, an SPT amendment should not be made merely because there is a difference in figures. Every amendment should be supported by relevant facts, evidence, analysis, adjustments, and a clear understanding of its impact on the tax return. This ensures that the amendment process has a clear and accountable audit trail.
What Should Be Prepared Before Amending an SPT?
One of the key points emphasized in KBA Consultant’s training is that the amendment process should not begin directly in Coretax. Taxpayers should first prepare the necessary working papers and reconcile the data to be reported.
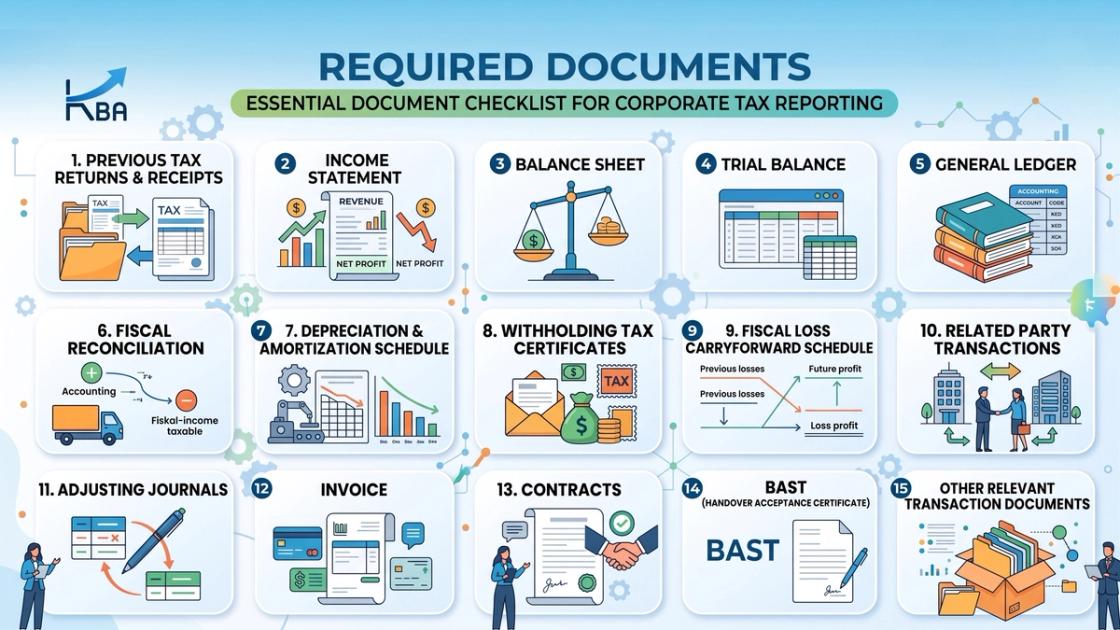
Documents to be prepared include the previously filed SPT and BPE, income statement, balance sheet, trial balance, general ledger, fiscal reconciliation, depreciation and amortization schedules, withholding or collection tax documents, fiscal loss carryforward schedules, related-party transactions, adjustment journals, invoices, contracts, BAST documents, and other relevant transaction documents.
Participants were also introduced to the amendment bridge, a table that compares the previously filed SPT with the adjustments made and the resulting position after the amendment. This approach helps ensure that every change in the figures has a clear rationale and supporting documentation.
How Is an SPT Amended Through Coretax?
Once all relevant data and documents have been prepared, the process can proceed through Coretax DJP. The taxpayer or an authorized party can log in and impersonate the Corporate Taxpayer’s account. The user then creates an SPT draft by selecting Corporate Income Tax, Annual SPT, the relevant tax year, and the Amendment option.
Once the previous SPT is loaded by the system, all information must still be reviewed carefully. The review covers the taxpayer’s identification details, financial statements, income, fiscal adjustments, tax credits, affiliated transactions, depreciation, tax loss compensation, Article 25 Income Tax, and other relevant attachments.
An amended SPT essentially represents a complete tax return that replaces the previously filed return, rather than merely changing the figures that have been identified as incorrect.
KBA Consultant’s training provides participants with hands-on guidance on the procedures for accurately amending and filing the Annual Corporate Income Tax Return through the Coretax system.
Fiscal Reconciliation and Corporate Income Tax Calculation
In the amendment process, fiscal reconciliation is an essential component. Participants need to understand the relationship between commercial profit, positive fiscal adjustments, negative fiscal adjustments, and the resulting fiscal net income. Each adjustment must be reviewed based on the nature of the account, transaction facts, supporting documentation, applicable tax provisions, and the amount being adjusted.
Once the adjustments are finalized, the calculation is performed again to determine Taxable Income, Corporate Income Tax payable, tax credits, and the resulting underpayment or overpayment position. KBA Consultant also emphasizes the importance of maintaining an independent calculation within the working papers, ensuring that Coretax is not the sole basis for the calculation.
Payment, Filing, and Documentation
If the amendment results in additional tax payable, the taxpayer must make the required payment through the available mechanisms, such as a tax deposit or billing code. Once the payment and data entry processes have been completed, the SPT is electronically signed and filed through Coretax.
It is equally important to ensure that the SPT status has changed to “Filed”, rather than remaining in Draft or Awaiting Payment status.
After successful filing, the Amended BPE should be downloaded and retained together with the SPT, working papers, payment evidence, fiscal reconciliation, and other supporting documents. Complete documentation will help taxpayers trace the basis of the amendment should clarification or further tax administration review be required in the future.
Strengthening Tax Knowledge in the Coretax Era
Through this Tax Training Program, KBA Consultant is committed to providing tax knowledge that goes beyond system operation and emphasizes accuracy, analysis, and compliance.
A properly prepared SPT amendment is not simply a matter of changing figures. It involves a clear process covering the underlying facts, supporting evidence, tax treatment, adjustments, their impact, and the amended SPT itself.
Conclusion
Overall, amending the Annual Corporate Income Tax Return in the Coretax era requires taxpayers to focus not merely on changes in figures, but also on the accuracy of the analysis and completeness of supporting evidence. Thorough preparation through the development of working papers outside the system is a key step before execution in Coretax.
Through this training, KBA Consultant emphasizes that a well-prepared amendment should be structured, supported by a clear audit trail, and completed through proper documentation, enabling taxpayers to maintain compliance and credibility with greater confidence.